
Fixed vs Floating Home Loan Interest Rate: Which Is Better
A practical comparison of fixed and floating home loan interest rates in India, including real cost scenarios, to help you choose the right structure for your loan.
The Core Difference
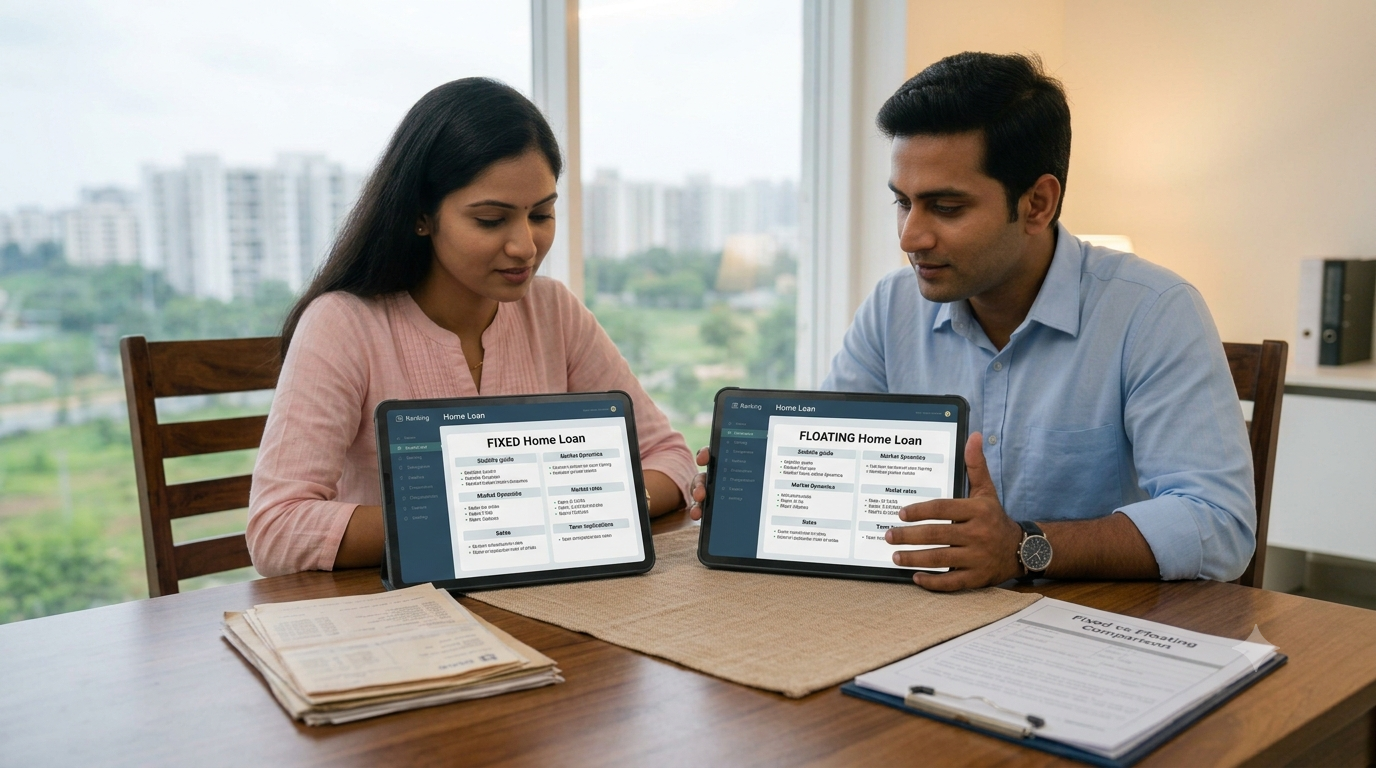
A fixed-rate home loan keeps your interest rate unchanged for a set period (or in rarer cases, the full tenure), giving you predictable EMIs regardless of what happens in the broader interest rate environment. A floating-rate loan moves up or down in line with the lender's benchmark rate, most commonly the RBI repo rate, meaning your EMI or tenure can change over time.
Why Floating Is the Default Choice for Most Borrowers
Floating rates are typically priced 0.5-1.5% lower than fixed rates at the time of sanction, because the lender isn't taking on long-term interest rate risk. Over a 15-20 year tenure, history shows rates cycle up and down, and floating-rate borrowers who stay the course generally pay less in total interest than those who locked into a fixed rate at a similar starting point.
When Fixed Makes Sense
If predictable, unchanging EMIs matter more to you than optimising for the lowest possible cost, perhaps because your income is tight relative to your EMI or you simply want budgeting certainty, a fixed rate removes the anxiety of rate hikes. It also suits borrowers who expect rates to rise significantly during their loan tenure and want to lock in current levels.
Read the Fine Print on 'Fixed'
Many loans marketed as fixed-rate are actually fixed only for an initial period, say 2-3 years, after which they convert to floating or are reset. True fixed-for-tenure loans are relatively rare in India's retail home loan market, so always confirm exactly how long the fixed period lasts before assuming full-tenure certainty.
A Hybrid Approach
Some lenders offer a hybrid structure, fixed for the first few years and floating thereafter, which can suit borrowers who want short-term certainty during a period of tight cash flow (such as right after a big move or career change) while still benefiting from floating rates long-term.
Get Guidance Matched to Your Risk Comfort
There's no universally correct answer, it depends on your income stability, risk tolerance and the current rate cycle. Perfect Solutions walks you through real numbers for both structures based on your specific loan amount and tenure, so your choice is based on your comfort and math, not a lender's default recommendation.
Common questions
Frequently asked questions
Can I switch from fixed to floating rate later?
Many lenders allow conversion between rate types, usually for a small conversion fee, so check your loan agreement for this clause before signing.
Does a floating rate mean my EMI changes every month?
No. Floating rates typically reset periodically (often quarterly, in line with repo rate reviews), and depending on the lender's policy, either your EMI or your tenure adjusts to reflect the new rate, not necessarily every single month.
Which is riskier, fixed or floating?
Floating carries the risk of your EMI/tenure increasing if rates rise, while fixed carries the 'risk' of paying more than the market rate if rates fall after you lock in. Neither is universally riskier; it depends on the rate cycle and your personal risk tolerance.
Want the real numbers for your loan?