
Home Loan EMI Calculator: How to Calculate Your Monthly EMI
Learn how home loan EMI is calculated, see real examples at different interest rates and tenures, and discover ways to reduce your monthly EMI burden.
What Is an EMI and Why It's More Than Just 'Loan ÷ Months'
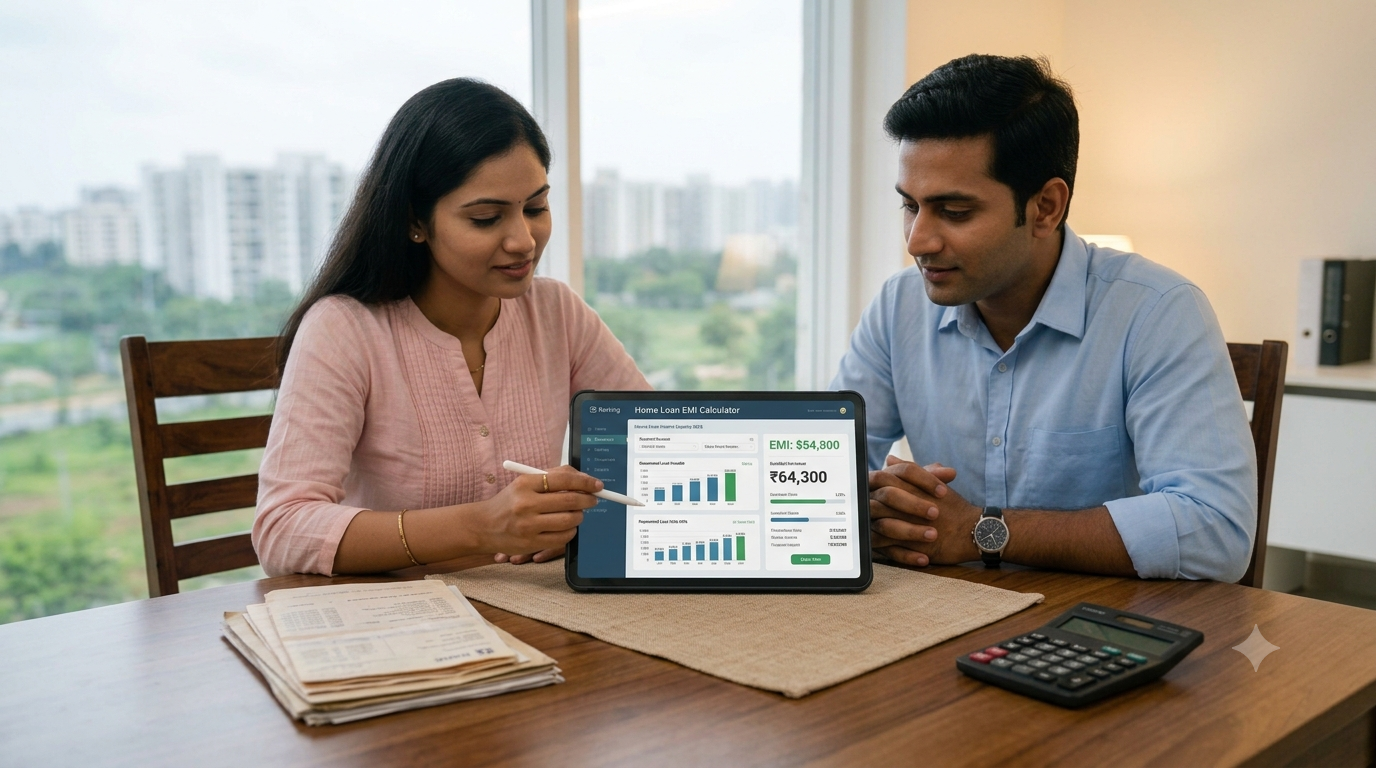
Your Equated Monthly Instalment, or EMI, is a fixed monthly payment that covers both a portion of the principal you borrowed and the interest charged on the outstanding balance. In the early years of a home loan, a much larger share of each EMI goes towards interest, and only in the later years does the principal component overtake it, which is why prepaying early has an outsized effect on total interest paid.
The EMI Formula Explained Simply
EMI is calculated using the formula EMI = P × r × (1+r)^n / [(1+r)^n − 1], where P is the loan principal, r is the monthly interest rate (annual rate divided by 12 and by 100), and n is the total number of monthly instalments. You rarely need to compute this by hand since every bank and loan platform offers a free EMI calculator, but understanding the formula helps you see why tenure and rate both swing your EMI significantly.
Real Examples at Different Loan Amounts
A ₹40 lakh loan at roughly 8.5% for 20 years works out to an EMI of approximately ₹34,700 a month, with total interest paid over the tenure close to ₹43 lakh. Stretch the same loan to 25 years and the EMI drops to around ₹32,200, but total interest paid rises to nearly ₹56 lakh. This trade-off between monthly affordability and total cost is the single most important decision in structuring a home loan.
How Tenure and Rate Changes Affect Your EMI
A longer tenure lowers your EMI but increases total interest paid; a shorter tenure raises your EMI but saves substantially on interest. Even a small rate difference compounds meaningfully over a 20-year loan, which is why comparing offers across lenders before signing, rather than after, is worth the extra week of effort.
Practical Ways to Reduce Your EMI Burden
Making a larger down payment reduces the principal and therefore the EMI. Choosing a step-up EMI structure, where instalments start lower and increase as your income grows, can help young earners buy sooner. Refinancing or doing a balance transfer to a lower-rate lender partway through the tenure is another effective lever many borrowers overlook.
Talk to Us Before You Lock In a Tenure
Perfect Solutions helps you model different tenure and rate combinations against your actual monthly budget and future income growth, so you choose an EMI structure that is comfortable today and efficient over the full loan life, not just the one the bank defaults to offering.
Common questions
Frequently asked questions
Does a longer tenure always mean I pay more interest overall?
Yes, generally. A longer tenure reduces your monthly EMI but increases the total interest paid over the life of the loan, since interest accrues for a longer period.
Can I change my EMI amount after taking the loan?
Yes, through a part-prepayment (which reduces either EMI or tenure, your choice with most lenders) or by refinancing to a different lender or rate structure via a balance transfer.
Is a step-up EMI a good idea for a young salaried borrower?
It can be, if you have strong reason to expect income growth, since it lets you afford a larger loan initially with lower EMIs that increase later in line with expected salary hikes.
Want the real numbers for your loan?