
How to Improve Your CIBIL Score Before Applying for a Loan
Practical, proven steps to improve your CIBIL score before applying for a home loan or personal loan, and common mistakes that quietly damage your credit history.
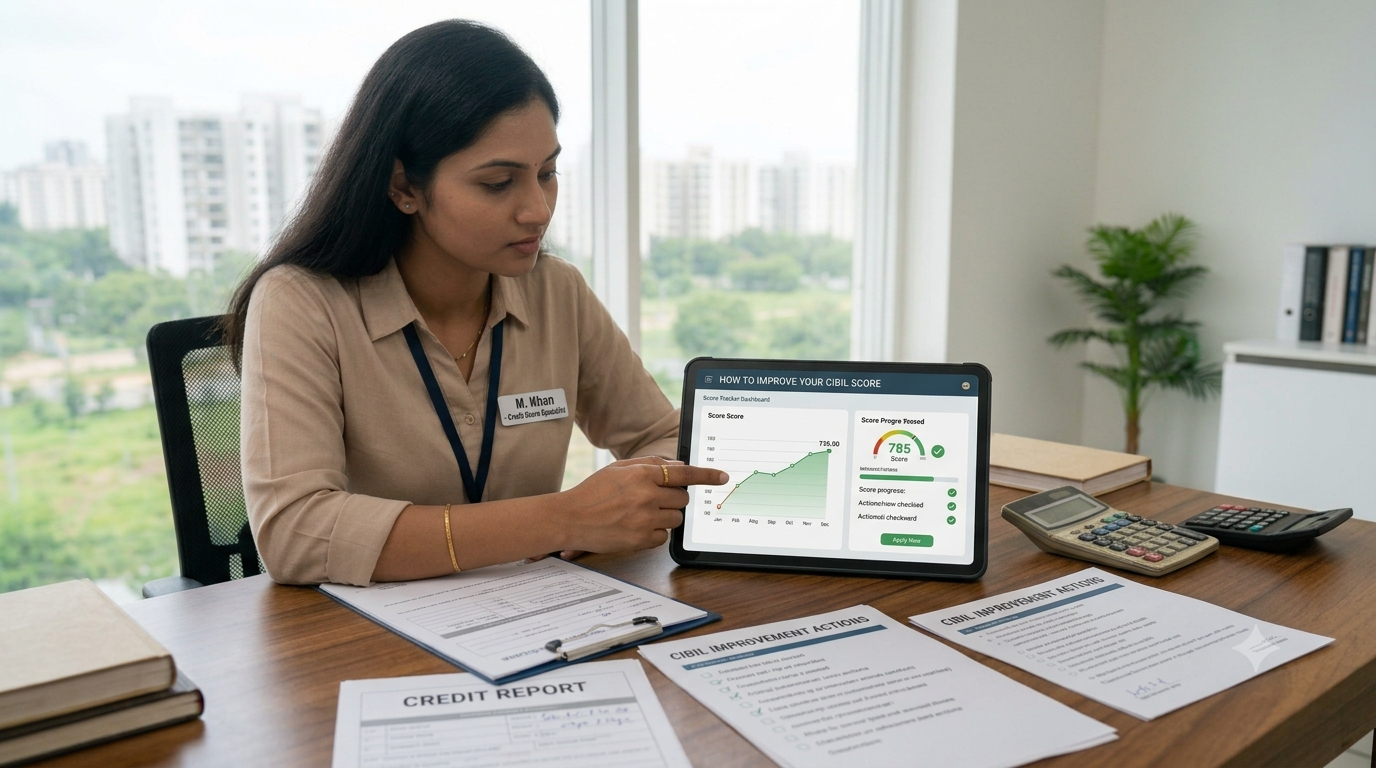
Start By Actually Reading Your Credit Report
Most people try to improve their score without ever checking what's actually pulling it down. Pull your report from CIBIL, Experian, Equifax or CRIF Highmark, all of which allow one free report per year, and go through every account listed. Errors, such as a closed loan still showing as active, or a payment wrongly marked late, are more common than most people expect, and disputing them can lift your score within a few weeks.
Pay on Time, Every Time, No Exceptions
Payment history is the single largest factor in your credit score. Even one payment missed by more than 30 days can stay on your report and affect your score for years. Setting up auto-debit for at least the minimum due on every credit card and EMI removes the human error factor that causes most accidental late payments.
Keep Credit Utilisation Low
Credit utilisation, the percentage of your total credit card limit you're using, should ideally stay under 30%. Someone with a ₹1 lakh limit who consistently carries a ₹70,000-80,000 balance, even if paid off eventually, will show as a higher-risk borrower than someone using ₹20,000-30,000 of the same limit. Paying down balances before the statement date, not just before the due date, helps because utilisation is often reported based on the statement balance.
Don't Apply for Multiple Loans or Cards at Once
Every loan or credit card application triggers a hard enquiry, and multiple hard enquiries in a short window signal credit hunger to lenders, which can lower your score and make each subsequent application harder to approve. Space out applications and only apply once you're reasonably confident of approval.
Keep Old Accounts Open
The length of your credit history matters. Closing your oldest credit card to 'simplify' your finances can actually shorten your average account age and hurt your score, so unless there's a fee-related reason to close it, it's often better to keep an old account open and lightly active.
We Help You Apply at the Right Time, to the Right Lender
Even with a good score, applying to the wrong lender for your profile wastes an enquiry and can dent your score for no benefit. Perfect Solutions pre-assesses your profile and matches it to lenders with the highest realistic approval chance, so your credit history stays protected through the process.
Common questions
Frequently asked questions
How long does a late payment stay on my credit report?
Negative marks like late payments typically remain visible on your credit report for up to several years, though their negative impact on your score generally lessens over time as you build a stronger recent payment history.
Does closing a credit card improve my CIBIL score?
Not usually. Closing a card, especially an older one, can reduce your overall available credit and shorten your credit history length, both of which can lower rather than improve your score.
How much can my score improve in 3 months?
With consistent on-time payments and low utilisation, a meaningful bump of 30-60 points is realistic in 3 months for many profiles, though the exact improvement depends on your starting point and what specifically was dragging the score down.
Not sure where you stand?