
Personal Loan vs Home Loan: Which One Should You Choose
Compare personal loans and home loans on interest rates, tenure, tax benefits and eligibility to decide which is the right financing option for your situation.
Two Very Different Tools for Two Different Jobs
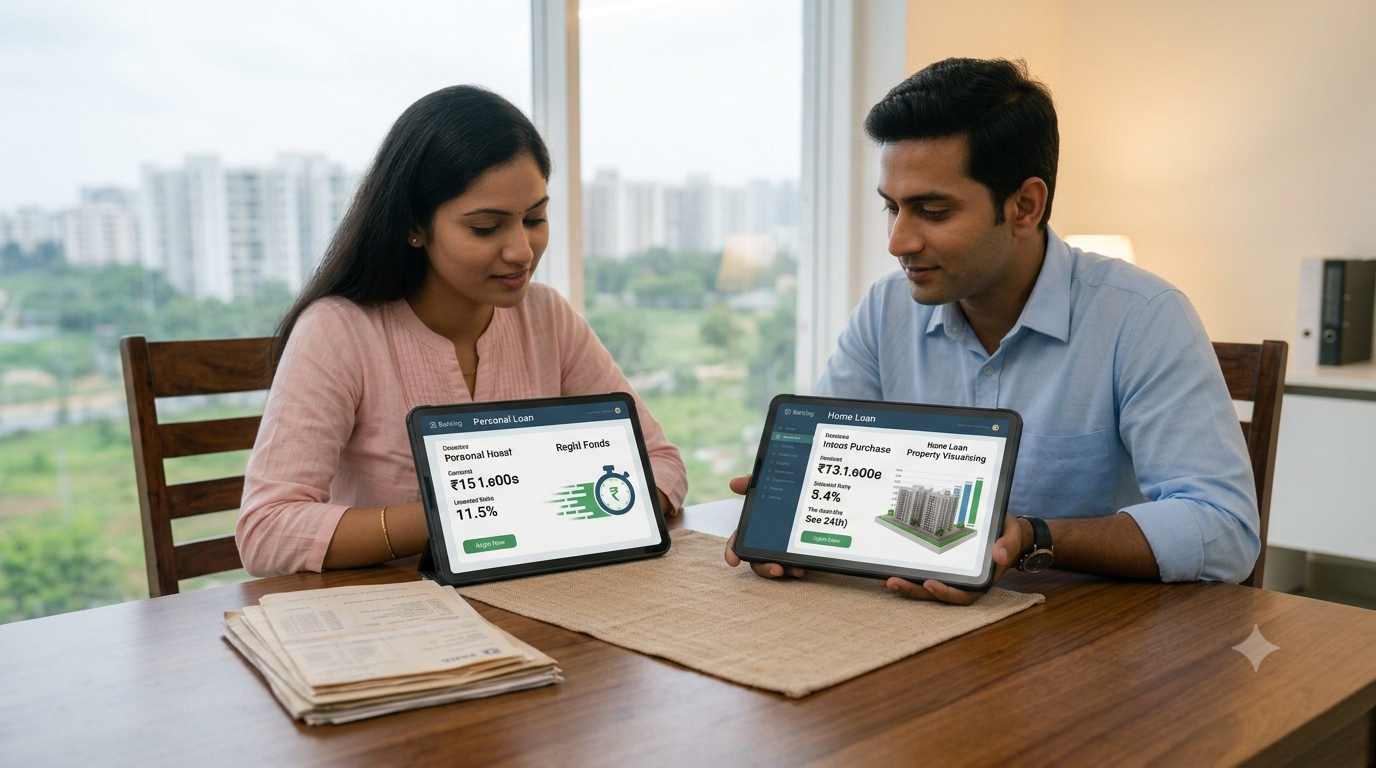
A home loan is a secured, purpose-specific loan for buying, constructing or renovating a property, while a personal loan is unsecured and can be used for virtually anything, a wedding, travel, medical emergency, or bridging a short-term cash gap. Comparing them head-to-head only makes sense when you're deciding how to fund a specific need, such as a down payment shortfall or interior work.
Interest Rate and Cost Comparison
Home loans carry some of the lowest interest rates available to individual borrowers because the property itself secures the lender's risk. Personal loans, being unsecured, are priced considerably higher, often several percentage points above home loan rates, because the lender has no collateral to fall back on if you default.
Loan Amount and Tenure Differences
Home loans can run into crores of rupees with tenures up to 30 years, matching the long-term nature of property ownership. Personal loans are capped much lower, typically up to ₹40-50 lakh depending on your income and lender, with tenures rarely exceeding five to seven years, which keeps the EMI relatively high despite the smaller principal.
When a Personal Loan Makes Sense Even If You Have a Home Loan
If you're short by a small amount for your down payment or need quick funds for registration and interiors, a short-tenure personal loan can bridge the gap faster than restructuring your home loan, since personal loans are typically disbursed within days with minimal documentation compared to the more elaborate property-verification process for a home loan top-up.
Tax Treatment Differs Significantly
Home loans come with meaningful tax deductions under Section 80C and 24(b), which materially reduce their effective cost. Personal loans generally offer no tax benefit unless the funds are proven to be used for business purposes or for property construction/renovation, which is rarely straightforward to establish.
Let Us Help You Pick the Right Structure
Sometimes the smartest move is a combination, a larger home loan at a low rate plus a smaller personal loan or LAP for the balance, rather than forcing everything into one product. Perfect Solutions can model both paths against your total cost of borrowing so you make an informed choice, not a default one.
Common questions
Frequently asked questions
Which loan is cheaper, personal loan or home loan?
Home loans are almost always cheaper on a per-rupee basis because they are secured against the property, while personal loans carry a materially higher interest rate due to being unsecured.
Can I use a personal loan for a home down payment?
It's possible, but most lenders prefer your down payment to come from your own savings rather than borrowed funds, and using a personal loan for this purpose can also affect your home loan eligibility calculation since it adds to your existing obligations.
Is it better to top up my home loan or take a fresh personal loan?
If your need is directly related to the property (renovation, furnishing) and your home loan allows a top-up at a lower rate than a personal loan, a top-up is usually more economical, subject to processing time being acceptable for your need.
Not sure which loan fits?